# Verifying Economic Finality in Outsourced Settlement Agents

A Banking Board Decision on the Result Purchased

Author: Phil Hatch
Publisher: Akholi
Paper ID: AAO-081
Published: October 23, 2026
Language: en
Canonical: https://akholi.com/papers/verifying-economic-finality-in-outsourced-settlement-agents/
Audience: Bank COO, operations risk executive and CFO

Bank boards should require settlement services to distinguish an agent’s completed instruction from the accepted economic and legal end state. Service scope, evidence, and unresolved obligations must reflect the transaction, infrastructure, and jurisdiction concerned.

<h2 id="section-1">Define the End State Before Buying Execution</h2>
<p>The board should ask management what a provider means when it reports a settlement task complete. Preparing an instruction, submitting it, receiving technical acceptance, posting a ledger entry, and achieving settlement finality are different states. The contract and executive reporting should not collapse them into one success measure.</p>
<p>The CPSS-IOSCO principles for <a href="https://www.bis.org/publications/principles-financial-market-infrastructures.pdf">financial market infrastructures distinguish settlement finality and exchange-of-value risks.</a><sup id="ref-1"><a href="#note-1" aria-label="Note 1">1</a></sup> Their scope is financial market infrastructures; they are not a universal rule directly governing every outsourcing provider. The bank should identify the applicable infrastructure rules and local legal conclusions for its service.</p>
<p>Define the purchased outcome, affected assets and accounts, required time, relevant confirmations, and outstanding counterparty obligations. Management should explain which event establishes completion and which evidence can support that conclusion independently of the provider agent’s own message.</p>
<h2 id="section-2">Follow the Transaction Across System Boundaries</h2>
<p>A provider agent may complete its internal sequence while a receiving system queues, rejects, or partially processes the instruction. Subsequent correction can alter the final state. The bank needs a connected transaction history rather than separate green indicators from each component.</p>
<p>The <a href="https://akholi.com/outsourcing-2026-agentic-ai-tier-1-banks/part-2-five-failure-categories/">study</a> <a href="https://akholi.com/outsourcing-2026-agentic-ai-tier-1-banks/part-3-governance-oversight-control/">reports fragmented visibility and completion messages inconsistent with results.</a><sup id="ref-2"><a href="#note-2" aria-label="Note 2">2</a></sup> It does not establish settlement losses or legal finality. The mechanism warrants testing where a service’s commercial completion point precedes the economic result the bank needs.</p>
<p>For a hypothetical asset-and-cash exchange, confirmation of one leg should not imply completion of the other. Record each leg, pending condition, exception owner, and consequence. Where finality is uncertain, report the uncertainty explicitly instead of treating a generated confirmation as conclusive.</p>
<h2 id="section-3">Use a Settlement End State Record</h2>
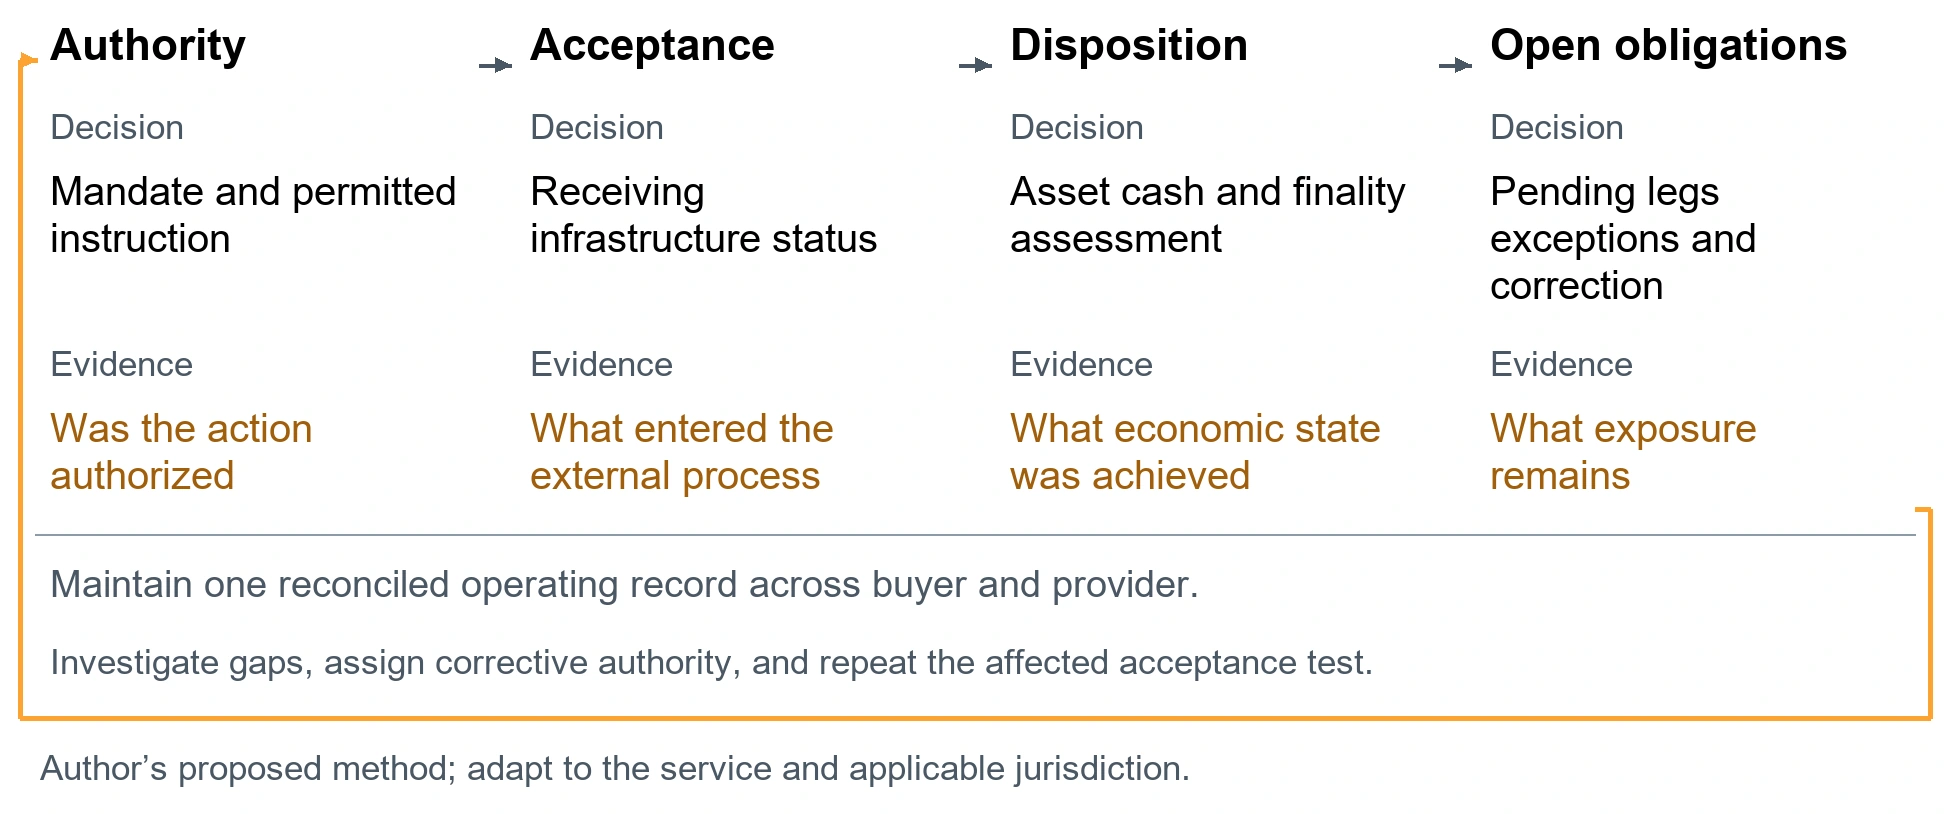
<p>Figure 1 proposes four layers: instruction authority, infrastructure acceptance, economic disposition, and unresolved obligations. Identify the authoritative source for each layer. Preserve retries, reversals, human corrections, and material differences between intended and observed results.</p>
<p>Management should assign ownership of failed and incomplete handoffs. A case should not fall between the provider’s contractual boundary and the bank’s receiving operations. Define the action, evidence, and authority needed to resolve the outstanding state before a deadline or further exposure arises.</p>
<p><a href="https://www.mayerbrown.com/en/insights/publications/2026/02/contracting-for-agentic-ai-solutions-shifting-the-model-from-saas-to-services">Mayer Brown</a>’s agentic services analysis connects defined authority with outcome-based performance obligations.<sup id="ref-3"><a href="#note-3" aria-label="Note 3">3</a></sup> Applied here, the commercial terms should state which end state earns acceptance and what cooperation is required when technical completion and economic disposition diverge.</p>
<figure><img loading="lazy" src="https://akholi.com/wp-content/uploads/2026/10/081-f1.webp" width="1950" height="814" alt="The settlement end state record. Authority. Decision: Mandate and permitted instruction. Evidence: Was the action authorized. Acceptance. Decision: Receiving infrastructure status. Evidence: What entered the external process. Disposition. Decision: Asset cash and finality assessment. Evidence: What economic state was achieved. Open obligations. Decision: Pending legs exceptions and correction. Evidence: What exposure remains. Maintain one reconciled operating record across buyer and provider.. Investigate gaps, assign corrective authority, and repeat the affected acceptance test.. Author’s proposed method; adapt to the service and applicable jurisdiction."><figcaption>Figure 1. The settlement end state record<small><a href="https://akholi.com/outsourcing-2026-agentic-ai-tier-1-banks/">Phil Hatch, proposed framework developed for this paper.</a></small></figcaption></figure>
<h2 id="section-4">Separate Correction from Reversal of Finality</h2>
<p>Stopping an agent prevents further action only within the systems it controls. It does not necessarily cancel an instruction already accepted by an external infrastructure. Management should identify irrevocability points, permitted cancellation routes, and corrective transactions with appropriate legal and operational specialists.</p>
<p>EU, UK, Swiss, US, and other markets differ by instrument, infrastructure, account relationship, and law. Obtain specific conclusions rather than one global statement that all agent actions are reversible. Preserve the applicable rule and evidence for each material service route.</p>
<p>Recovery plans should reconcile the original transaction and any compensating action. A corrective payment may repair an effect without erasing the original event. Executive reporting should distinguish containment, operational recovery, financial correction, and residual claims or obligations.</p>
<h2 id="section-5">Approve the Service Against the Consequential Result</h2>
<p>A reasonable objection is that the provider cannot control every external system. The bank should allocate dependencies fairly while keeping the final result visible. The supplier can own defined actions and evidence even where the bank retains the ultimate transaction or counterparty exposure.</p>
<p>Before granting consequential execution authority, require representative end-to-end cases, including rejection, partial completion, delayed confirmation, and correction. Reconcile each to authoritative records. Restrict the scope where the evidence cannot establish the accepted end state or the treatment of uncertainty.</p>
<p>The board should approve settlement automation on the basis of a defensible transaction outcome. Faster instruction generation can be valuable, but the bank’s obligation extends to what happened to the assets, cash, and remaining commitments. That is the result the service must make visible.</p>
<h2 id="section-6">Evidence and Source Note</h2>
<p>The study is a nonrepresentative cross-section of 850 vendor delivery-team <a href="https://akholi.com/outsourcing-2026-agentic-ai-tier-1-banks/introduction/">respondents</a> on 150 engagements serving Tier 1 financial institutions, collected during January–June 2026. Neither banks nor vendors corroborated the accounts. It establishes reported experience, not causation, legal breach, or market prevalence. The author-supplied version 1.8.2 is dated November 1, 2026 and is cited as a forthcoming manuscript consulted October 23, 2026.<sup id="ref-4"><a href="#note-4" aria-label="Note 4">4</a></sup></p>
<p>This is an analytical decision paper based on the supplied study and selected primary public sources checked through October 23, 2026. The original contribution is a settlement end-state record separating technical completion, economic disposition, legal finality, and unresolved obligations across the outsourcing boundary. The proposed method has not been independently validated. Legal requirements depend on the entity, activity, jurisdiction, and effective provisions; supervisory observations, research, and professional commentary have distinct authority.</p>
<h2 id="notes">Notes</h2><ol class="akp-notes"><li id="note-1">Committee on Payment and Settlement Systems and Technical Committee of the International Organization of Securities Commissions, <i>Principles for Financial Market Infrastructures</i> (Committee on Payment and Settlement Systems and Technical Committee of the International Organization of Securities Commissions, April 2012), principles 8, 12, and 17; scope in sec. 1, <a href="https://www.bis.org/publications/principles-financial-market-infrastructures.pdf">https://www.bis.org/publications/principles-financial-market-infrastructures.pdf</a>. <a href="#ref-1" aria-label="Return to note 1">↩</a></li><li id="note-2">Phil Hatch, <i>Agentic AI Outsourcing at Tier 1 Financial Institutions: Full Study Report</i>, version 1.8.2 (Akholi, forthcoming manuscript dated November 1, 2026), Part 2, sec. 5.1, “Agent Actions Visible Only Inside Each Firm’s Own Tools”, <a href="https://doi.org/10.2139/ssrn.7164559">https://doi.org/10.2139/ssrn.7164559</a>; Hatch, <i>Agentic AI Outsourcing</i>, Part 3, AI Technology, sec. 4.1, “Accuracy of the Tools’ Own Success and Failure Reports,” indicator C172. <a href="#ref-2" aria-label="Return to note 2">↩</a></li><li id="note-3">Rohith P. George et al., “Contracting for Agentic AI Solutions: Shifting the Model from SaaS to Services,” Mayer Brown, February 17, 2026, secs. 1–6, <a href="https://www.mayerbrown.com/en/insights/publications/2026/02/contracting-for-agentic-ai-solutions-shifting-the-model-from-saas-to-services">https://www.mayerbrown.com/en/insights/publications/2026/02/contracting-for-agentic-ai-solutions-shifting-the-model-from-saas-to-services</a>. <a href="#ref-3" aria-label="Return to note 3">↩</a></li><li id="note-4">Hatch, <i>Agentic AI Outsourcing</i>, Introduction, “Executive Summary” and “Evidentiary Basis and Its Limits”. <a href="#ref-4" aria-label="Return to note 4">↩</a></li></ol>
<h2 id="bibliography">Bibliography</h2><ul class="akp-bibliography"><li>Committee on Payment and Settlement Systems and Technical Committee of the International Organization of Securities Commissions. <i>Principles for Financial Market Infrastructures</i>. Committee on Payment and Settlement Systems and Technical Committee of the International Organization of Securities Commissions, April 2012. <a href="https://www.bis.org/publications/principles-financial-market-infrastructures.pdf">https://www.bis.org/publications/principles-financial-market-infrastructures.pdf</a>.</li><li>George, Rohith P., Joe Pennell, Brad L. Peterson, and Oliver Yaros. “Contracting for Agentic AI Solutions: Shifting the Model from SaaS to Services.” Mayer Brown. February 17, 2026. <a href="https://www.mayerbrown.com/en/insights/publications/2026/02/contracting-for-agentic-ai-solutions-shifting-the-model-from-saas-to-services">https://www.mayerbrown.com/en/insights/publications/2026/02/contracting-for-agentic-ai-solutions-shifting-the-model-from-saas-to-services</a>.</li><li>Hatch, Phil. <i>Agentic AI Outsourcing at Tier 1 Financial Institutions: Full Study Report</i>. Version 1.8.2. Akholi. Forthcoming manuscript dated November 1, 2026. Author-supplied manuscript consulted October 23, 2026. <a href="https://doi.org/10.2139/ssrn.7164559">https://doi.org/10.2139/ssrn.7164559</a>.</li></ul>
