The chief financial officer should require a common definition of an accepted outcome before comparing an agentic service with its predecessor. The outcome should describe the business function delivered at an agreed quality, service level, and control standard. An attempted task or generated document is not automatically an accepted business result.
The buyer’s decision denominator should be accepted outcomes within a defined period and workload. The numerator should include all relevant buyer costs: provider fees, retained work, integration, oversight, rework, assurance, and other attributable expense. Identify transition investment separately so recurring unit cost and investment return do not become confused.
McKinsey’s August 2026 economics analysis recommends a total-cost perspective and identifies human oversight as a potentially substantial cost. Its examples are not a universal outsourcing benchmark. The CFO should obtain the actual cost and acceptance evidence for the service rather than import a published cost share.1
A hypothetical claims-administration agent may produce a recommendation that requires buyer review, missing-document retrieval, correction, and final entry. The provider’s completed-task count can rise while the buyer absorbs more effort. The business comparison should include that retained work and distinguish routine review from avoidable rework.
The study reports manual alteration across all sampled engagements and describes incomplete work behind success flags. Those mechanisms explain why the CFO should reconcile output claims with accepted outcomes. They do not establish a universal cost penalty, nor do they prove that human intervention makes an agentic service uneconomic.2
Legitimate hybrid delivery should be evaluated on its complete economics. A service with necessary human verification can create value if its accepted outcomes cost less or perform better within the agreed risk boundary. The issue is whether the human contribution is visible and included, rather than whether the provider can describe the process as autonomous.
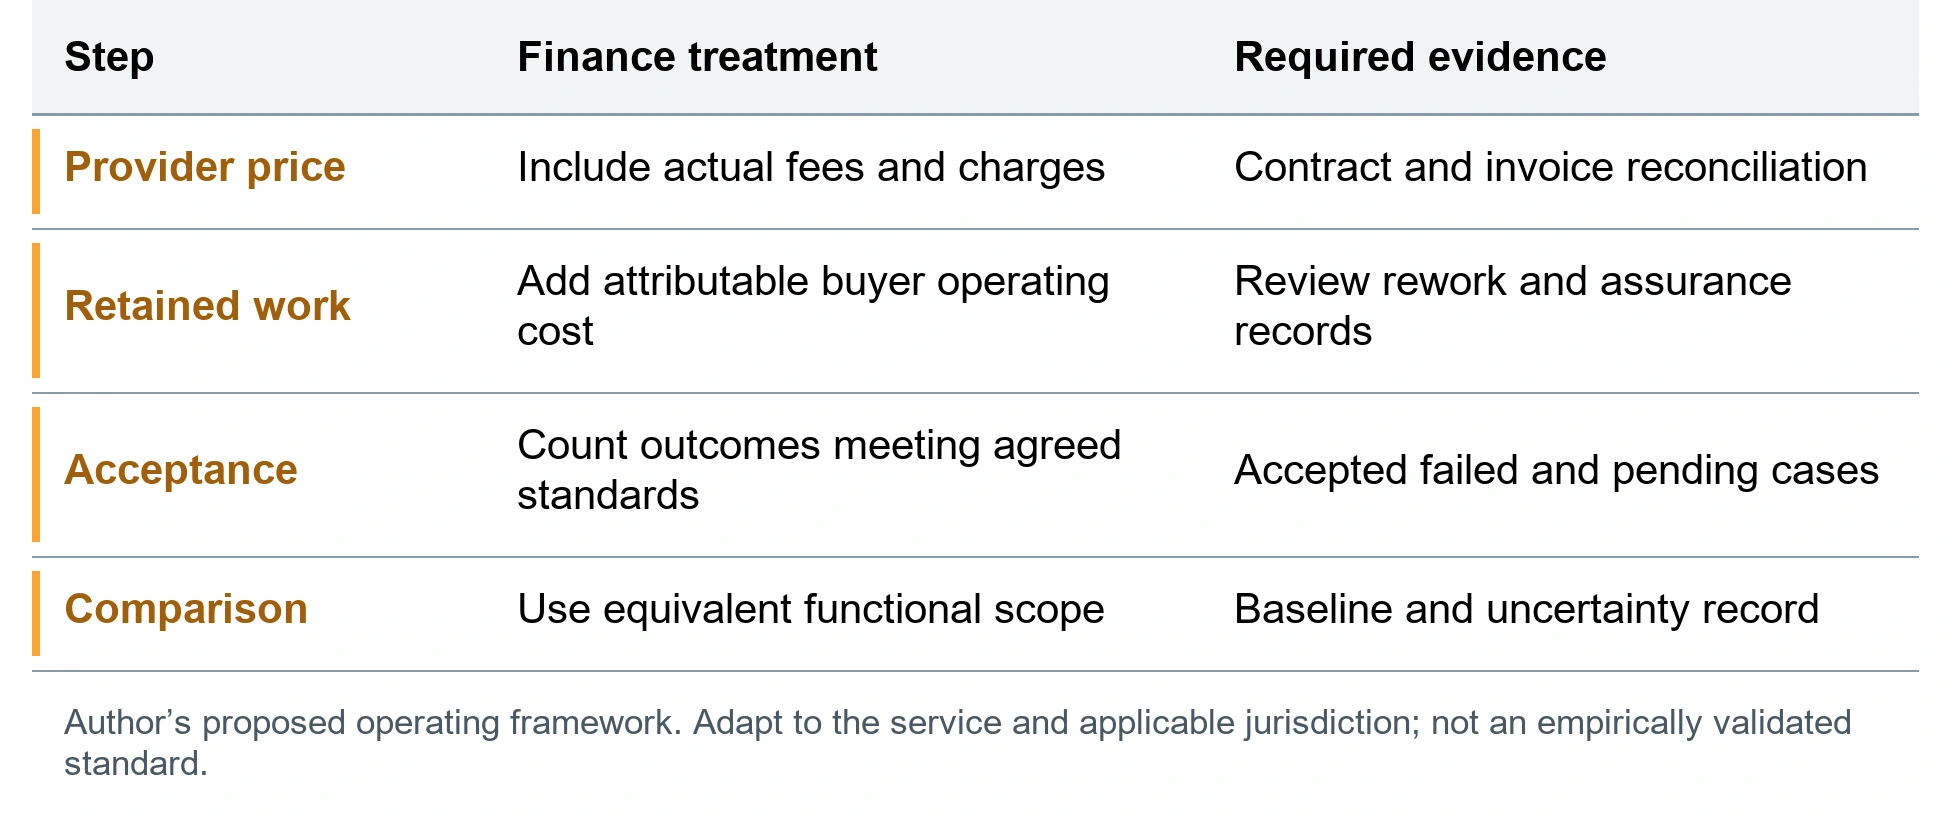
Figure 1 proposes the bridge between the provider price and the buyer’s economic result. Establish provider fees, add incremental retained and shared costs, reconcile acceptance, and compare the same workload. If the buyer pays a bundled fee, do not add the provider’s internal labor again. Internal supplier costs belong in a separate delivery-economics view.
Consider an explicitly hypothetical annual comparison. A legacy service costs $1 million for 100,000 accepted outcomes, or $10 each. An agentic proposal has $700,000 in fees and $250,000 in retained and attributable operating cost, also for 100,000 accepted outcomes. Its recurring unit cost is $9.50, a 5% reduction, before transition investment.
If the same $950,000 produces only 90,000 accepted outcomes in the period, unit cost becomes approximately $10.56, above the legacy comparison. This sensitivity illustrates the denominator’s importance; it is not study data or a forecast. Management must investigate missing outcomes and service consequences rather than report only the lower provider fee.
Faster work can release staff time without reducing cash expense. Finance should identify the mechanism of capture: reduced external spend, avoided recruitment, eliminated overtime, increased accepted volume, or another evidenced benefit. Retained capacity can have value, but it should not be booked as a cash saving without a corresponding financial change.
BCG’s September 2026 research associates enterprise AI value with strategic clarity, operating capability, and outcome tracking. It provides broader market context, not causal proof that a particular outsourcing intervention produces a return. The CFO’s acceptance ledger must establish the result for the actual service.3
Quality and risk need explicit treatment. A cheaper outcome that fails the required standard is not comparable. Where a service improves timeliness or quality, report the measured improvement separately and explain its financial treatment. Do not monetize an avoided incident without a defensible method and sufficient evidence.
The legacy and agentic comparison should use equivalent scope, workload complexity, acceptance rules, and measurement periods. If the process changes fundamentally, compare the business function rather than old process steps. Record demand shifts, policy changes, and other concurrent interventions that limit attribution.
A lower unit cost can still produce an unattractive investment when transition cost is high or the benefit arrives late. The CFO should therefore use the recurring comparison as an input to a separately stated cash-flow appraisal. Include the investment, timing, discounting method where used, and benefit capture. This paper’s unit-cost example does not calculate investment ROI; treating its 5% operating reduction as an investment return would use the wrong denominator.
For a global service, preserve local labor costs, service obligations, currencies, and acceptance conditions. EU, UK, Swiss, and US operations may require different retained controls. Normalize exchange rates and inflation only under a stated method. A blended average can conceal a service that is economical in one location and unsuitable in another.
Where the baseline is missing, reconstruct it from invoices, case records, time evidence, and service measures. Label the result as an estimate and show uncertainty. Management can make a conditional investment decision under uncertainty, but should not call an unsupported estimate measured ROI.
The CFO should require periodic reconciliation of fees, retained effort, acceptance, and captured benefit. Escalate unexplained increases in rework, missing outcomes, or cost outside the original boundary. A lower invoice should not close the review while the buyer’s operating burden rises elsewhere.
The decision is whether the service improves the cost and performance of the purchased business function after all relevant buyer work is counted. Approve expansion on that evidence, with transition investment and uncertainty visible. A defensible outcome-cost comparison is the foundation for the broader investment decision.
The study is a nonrepresentative cross-section of 850 vendor delivery-team respondents on 150 engagements serving Tier 1 financial institutions, collected during January–June 2026. Neither banks nor vendors corroborated the accounts. It establishes reported experience, not causation, legal breach, or market prevalence. Its application here is a mechanism to investigate, not an estimate of conditions in other industries. The author-supplied version 1.8.2 is dated November 1, 2026 and is cited as a forthcoming manuscript consulted October 23, 2026.4
This is an analytical decision paper based on the supplied study and selected primary public sources checked through October 23, 2026. The original contribution is an executive accepted-outcome cost bridge. The numerical comparison is hypothetical and independently calculable. The proposed method has not been independently validated. Legal requirements depend on the entity, activity, jurisdiction, and effective provisions; supervisory observations, research, and professional commentary have distinct authority.